Ohio Legacy Law

Category: Asset Protection

Quick Summary: When a parent’s memory starts slipping or a health crisis hits, families in Hillsboro, Georgetown, West Union, and across Highland, Brown, and Adams Counties often assume court-supervised guardianship is the only way to step in and help. It isn’t. Under Ohio law, a properly executed power of attorney is a less restrictive alternative that a probate court must consider — and, when it’s already in place, it usually lets a family avoid guardianship altogether. Pursuant to Sup.R. 66 and R.C. 2111.02, an Ohio probate court is required to weigh less restrictive alternatives, like a valid power of attorney, before it will appoint a guardian. Ohio Legacy Law helps families throughout Southern Ohio put the right documents in place now, so a judge — not a stranger — isn’t the one deciding who cares for Mom or Dad later.


Frequently a son or daughter calls our Hillsboro office with some version of the same story: Dad’s doctor mentioned dementia, the bank froze an account after a suspicious withdrawal, or a sibling in another state wants to know “who’s in charge” now that Mom can’t manage her own affairs. The instinct is almost always the same — “I guess we need to get guardianship.”

Sometimes that’s true. But in a surprising number of cases, it isn’t necessary, and it isn’t even the first option Ohio law allows a probate court to consider. Understanding the real difference between a power of attorney and a guardianship — and knowing which one actually fits your family’s situation — can save months of court proceedings, thousands of dollars, and a painful loss of independence for the parent you’re trying to protect.

What a Power of Attorney Actually Does

A power of attorney (POA) is a document your parent signs, while still legally competent, naming someone — usually a spouse, adult child, or trusted relative — to act on their behalf. Ohio recognizes two main types under the Ohio Uniform Power of Attorney Act, R.C. Chapter 1337:

  • Financial (durable) power of attorney — Authorizes an agent to pay bills, manage bank and investment accounts, handle real estate, and deal with Social Security, pensions, and Medicaid applications.

  • Healthcare power of attorney — Authorizes an agent to make medical decisions and speak with doctors and hospitals when the principal cannot, governed by R.C. 1337.11 through 1337.17.

A POA is private, inexpensive, and effective almost immediately once it’s signed and notarized. There is no lawsuit, no court hearing, and — critically — your parent doesn’t lose any of their own legal rights. They simply give someone else the authority to act alongside them. For families in Mount Orab, Ripley, Greenfield, Peebles, and Manchester who are watching a parent’s independence slip gradually rather than all at once, a POA is often the entire solution.

What Guardianship Actually Involves

Guardianship is a different animal entirely. It is a court proceeding filed in the probate division of common pleas court — in Highland County, that’s the Highland County Probate Court in Hillsboro; in Brown County, the Brown County Probate Court in Georgetown; in Adams County, the Adams County Probate Court in West Union. A guardianship case requires:

  • A formal application and filing fees

  • A statement of expert evaluation (medical or psychological) documenting incapacity

  • Notice to the proposed ward and next of kin

  • A court hearing, often with a court-appointed attorney representing the proposed ward

  • Ongoing court supervision, including annual accountings and reports for as long as the guardianship lasts

  • In many cases, a bond and background check for the guardian

Guardianship strips the ward of significant legal rights — the right to manage money, make medical decisions, choose where to live, even in some cases the right to vote or marry — and hands that authority to a court-supervised guardian instead. It is sometimes the only realistic option, particularly when a parent never signed a POA and has since lost the capacity to sign one, or when family members are in open conflict over who should be in charge. But it is slower, far more expensive, and far more restrictive than most families expect.

Ohio Law Requires the Less Restrictive Option to Be Considered First

This is the part most families never hear until they’re already sitting in a probate courtroom: Ohio does not let a court reach for guardianship as a first resort. Under R.C. 2111.02, evidence of a less restrictive alternative to guardianship — such as an existing power of attorney — must be introduced and considered by the court, and a judge may deny the guardianship application entirely if a less restrictive alternative already exists (Ohio Revised Code § 2111.02). The Ohio Rules of Superintendence, Sup.R. 66, reinforce the same principle for guardians who are already appointed, directing that decisions must impose “the least limitations on the ward’s rights, freedom, or ability to control the ward’s environment” (Rules of Superintendence for the Courts of Ohio, Rule 66).

The Supreme Court of Ohio’s own guardianship resources are direct about it: “Pursuant to Sup.R. 66 and R.C. 2111.02, a probate court must explore the least restrictive alternatives before appointing a guardian,” and a properly executed power of attorney is specifically identified as one of those alternatives (Supreme Court of Ohio, Alternatives to Adult Guardianship).

Ohio Law Alert: If your family already has a valid, signed financial and healthcare power of attorney for your parent, a probate judge in Highland, Brown, or Adams County may not even grant a guardianship application over that parent’s objection — the existing POA has to be weighed first and may be enough to allow you to assist your loved one and protect their best interests.

Power of Attorney vs. Guardianship: Side by Side

Power of Attorney Guardianship
Who decides Your parent, while competent, chooses their own agent A probate judge chooses and supervises the guardian
Court involvement None to set up; no ongoing court oversight Full court process, plus ongoing annual reporting
Cost Typically a flat drafting fee Filing fees, evaluation costs, attorney fees, bond premiums, and recurring accounting costs
Timeline Can be signed and effective within days Can take weeks to months, longer if contested
Parent’s rights Retained in full; agent acts alongside the parent Significantly reduced or removed, depending on scope
Flexibility Can be revised or revoked while the parent has capacity Requires a court motion to modify or terminate
Best suited for Planning ahead, or early-to-moderate decline No POA in place, disputed capacity, family conflict, or suspected exploitation

When a Power of Attorney Isn’t Enough

A POA is not a substitute for guardianship in every case. Guardianship becomes necessary — and the “less restrictive alternative” argument falls away — when:

  • Your parent never signed a POA and has already lost the legal capacity to sign one now

  • The named agent under an existing POA is unwilling, unavailable, incapacitated themselves, or is suspected of financial exploitation

  • Family members disagree sharply about care decisions and someone needs a court order to resolve the conflict

  • A bank, hospital, or care facility refuses to honor a POA due to a technical defect in how it was executed

  • There is an urgent safety issue and no one currently holds legal authority to act

In these situations, a limited guardianship — one tailored narrowly to just the powers actually needed, leaving your parent’s other rights intact — is often preferable to a full guardianship, and R.C. 2111.02 specifically allows for that middle ground.

Pro Tip: Don’t wait for a crisis to find out whether your parent’s POA is still valid. Banks and hospitals in Hillsboro, Georgetown, and West Union increasingly reject older POA forms that don’t meet current statutory requirements. Have it reviewed before you need to use it.


What Families in Highland, Brown, and Adams Counties Should Do Now

If your parent is still able to understand and sign legal documents, the highest-leverage move you can make today is putting a durable financial power of attorney and a healthcare power of attorney in place — before a fall, a stroke, or a dementia diagnosis takes that option off the table. If your parent has already lost capacity and no POA exists, a guardianship filing in the Highland, Brown, or Adams County Probate Court may genuinely be the right and necessary path, and moving quickly matters.

Either way, this is not a decision to make from a downloaded form. Ohio Legacy Law works with families throughout Hillsboro, Greenfield, Leesburg, Georgetown, Ripley, Mount Orab, Aberdeen, West Union, Manchester, Peebles, and Winchester to determine which path actually fits your parent’s situation, draft documents that local banks and hospitals will honor, and — when guardianship truly is necessary — guide you through the probate court process from filing to final appointment.


Frequently Asked Questions

Q: If my parent already has a guardian, can we switch to a power of attorney instead?
A: Once a guardianship is established, ending it requires a motion to the probate court, not simply signing a new POA. The court will look at whether the ward’s capacity has improved or a less restrictive alternative — including a POA — is now appropriate under Sup.R. 66.

Q: Does a power of attorney expire if my parent becomes incapacitated?
A: No — a durable power of attorney is specifically designed to remain effective even after incapacity, which is exactly why it functions as an alternative to guardianship. A non-durable POA, by contrast, terminates on incapacity and would leave your family needing guardianship instead.

Q: Can more than one sibling be named on a power of attorney?
A: Yes, and it can be structured to require siblings to act jointly or to act independently, depending on your family’s dynamics. This is worth discussing carefully, since disagreements between co-agents are one of the more common reasons families end up in guardianship court anyway.

Q: Will the probate court in Highland, Brown, or Adams County automatically deny a guardianship if a POA exists?
A: Not automatically — the court still evaluates whether the POA adequately addresses your parent’s needs. But under R.C. 2111.02(C)(6), the court has the authority to deny guardianship where it finds a less restrictive alternative exists, so a well-drafted POA gives your family real leverage to avoid an unnecessary guardianship.

Protect Your Aging Parent the Right Way — Before a Crisis Forces the Issue

Whether your family needs a power of attorney, a healthcare directive, or guidance through a guardianship filing in Highland, Brown, or Adams County, Ohio Legacy Law can help you choose the path that actually protects your parent — and your family.

Call (937) 402-2348 to schedule a strategy session, or stop by our office at 338 West Main Street, Hillsboro, Ohio 45133 (Monday–Friday, 10 AM–5 PM; summer and holiday hours vary, please call ahead).

This article is provided for general informational purposes only and does not constitute legal advice. Every estate plan is different, and you should consult with an attorney regarding your specific circumstances.
 

Category: Asset Protection

When clients sit down with me to plan a trust, the conversation almost always comes back to one core question: “How do I make sure this money actually helps the people I love, instead of hurting them?” It is a question born of love, not distrust. You want your gift to be a blessing — not a burden, not a target, and not a source of conflict.

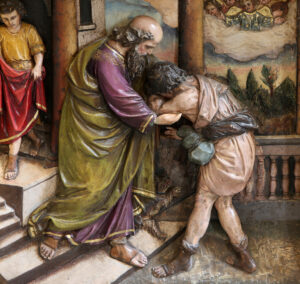
Most people have a story of someone who inherited something and squandered it.  One of the most well known and loved parables of Jesus is of the Prodigal Son, the classic example.

One of the most powerful, and most underused, tools for accomplishing that goal is the spendthrift clause.

The Basic Idea

A spendthrift clause (sometimes called a spendthrift provision) is language written into a trust that does two things at once. First, it prevents a beneficiary from voluntarily selling, assigning, or pledging their future interest in the trust before they actually receive a distribution. Second, and just as importantly, it prevents a beneficiary’s creditors from reaching into the trust to seize that interest before the money is paid out. Ohio law is explicit on this point: a spendthrift provision is only valid if it restrains both the voluntary and involuntary transfer of a beneficiary’s interest, or restrains involuntary transfer while allowing voluntary transfer only with a trustee’s consent (Ohio Revised Code § 5805.01).

In plain terms, until the trustee actually cuts a check or hands over property to the beneficiary, that money legally belongs to the trust — not to the beneficiary, and not to anyone the beneficiary owes money to.

Why This Matters for Your Goals as the Grantor

As the person creating the trust (the “grantor” or “settlor”), you are not just moving assets from one column to another. You are trying to accomplish something deeply personal: you want your children, grandchildren, or other loved ones to actually benefit from what you worked a lifetime to build. A spendthrift clause protects that vision in several concrete ways.

It shields the gift from creditors. Life happens. A beneficiary might face a lawsuit, a business failure, or unexpected debt years after you are gone. Under Ohio’s Trust Code, a creditor or assignee of a beneficiary generally cannot reach the beneficiary’s trust interest, or a distribution before the beneficiary actually receives it, so long as a valid spendthrift provision is in place (Ohio Revised Code § 5805.01(C)). Without that language, a creditor could potentially attach future distributions and take the inheritance you intended for your family before your loved one ever sees a dime of it.

It protects against poor decision-making and undue influence. Not every beneficiary is a sophisticated money manager, and not every beneficiary is immune to pressure from a persuasive friend, a struggling business partner, or a manipulative spouse. Addiction issues can cloud a beneficiaries decision making until they get clean.  Because a spendthrift clause prevents the beneficiary from assigning or borrowing against their future interest, it removes the temptation — and the legal mechanism — for someone to talk your beneficiary into signing away their inheritance for a quick loan or a bad investment.

It preserves your intent through a divorce. One of the most common reasons I recommend a spendthrift clause is divorce protection. Ohio courts have generally recognized that a spendthrift provision is enforceable against a beneficiary’s former spouse (Ohio Revised Code § 5805.02(C)), which helps keep inherited assets separate from marital property disputes rather than becoming a bargaining chip in a settlement.  Spendthrift provisions along with prenuptial agreements are important tools.  No one begins with the idea that a divorce will happen, but life happens and an inheritance can be another stumbling block in the relationship.

It gives the trustee room to act in the beneficiary’s true best interest. Because the assets stay inside the trust structure rather than becoming immediately reachable, the trustee can distribute funds according to the schedule and purposes you set — for education, for a first home, for health needs — rather than the assets being scooped up all at once by a claim you never anticipated.

The Limits You Should Know

A spendthrift clause is strong, but it is not absolute, and I always tell clients the truth about its boundaries rather than overselling it. Ohio law carves out specific exceptions. A spendthrift provision generally cannot be used to defeat a claim brought by a beneficiary’s child or spouse for court-ordered support, at least where distributions could be made for the beneficiary’s support, nor can it be used to defeat certain claims by the State of Ohio or the federal government (Ohio Revised Code § 5805.02(B)). If the trust is set up as a wholly discretionary trust, Ohio law provides an additional layer of protection — creditors generally cannot compel distributions or reach the beneficiary’s interest at all, spendthrift language or not (Ohio Revised Code § 5805.03).

For clients with heightened creditor-protection concerns — business owners, professionals in high-liability fields, or those simply wanting the strongest asset protection available under Ohio law — we can also discuss Ohio’s legacy trust statute, which offers additional statutory protections for self-settled trusts (Ohio Revised Code § 5816.03).

Making Your Gift a Blessing, Not a Liability

At the end of the day, estate planning is about more than paperwork — it is about making sure the people you love actually receive the benefit of what you leave them, on the terms and timeline that reflect your values. A well-drafted spendthrift clause is one of the simplest, most effective tools we have to keep your gift protected, keep your intent intact, and keep your family’s inheritance a source of security rather than stress.  Let’s talk about it.

If you are considering a trust, or want to review whether your existing trust includes strong spendthrift protection, I welcome the conversation. You can reach my office at (937) 402-2348 or jim@southwestohiolaw.com.

This article is provided for general informational purposes only and does not constitute legal advice. Every estate plan is different, and you should consult with an attorney regarding your specific circumstances.

— James E. Schroeder, Attorney at Law

STITAR, CROATIA - Return of the prodigal son, Relief on main altar in the church of Saint Matthew in Stitar, Croatia


Return of the prodigal son, Relief on main altar in the church of Saint Matthew in Stitar, Croatia

Category: Asset Protection

Crisis Medicaid estate planning involves strategies to protect assets and qualify for Medicaid when long-term care is urgently needed, such as a sudden nursing home admission. The goal is to meet Medicaid’s strict income and asset limits while preserving as much of your estate as possible for your family. Here are some key options, based on common practices in elder law and Medicaid planning:

1. Medicaid Asset Protection Trusts (MAPTs)

MAPTs are irrevocable trusts that can shield assets like your home or savings from being counted for Medicaid eligibility. Assets are transferred into the trust, and after Medicaid’s 5-year look-back period, they’re typically protected from estate recovery programs (MERP). In a crisis, this strategy may still be used, but transfers within the look-back period can lead to a penalty period of ineligibility, so timing is critical.

2. Gifting Assets Strategically

You can gift assets to family members, such as children or grandchildren, to reduce your countable assets. In a crisis, gifting up to 40-50% of assets is sometimes advised to lower your estate below Medicaid’s threshold (often $2,000 for an individual). However, any gifts made within the 5-year look-back period may trigger penalties, delaying Medicaid eligibility. This approach also risks loss of control—gifted assets could be spent or lost if the recipient faces financial trouble.

3. Spousal Protections

For married couples, strategies like spousal refusal or Medicaid-compliant annuities can help. Spousal refusal allows the healthy spouse to keep more assets (e.g., up to $130,000 in some states) by refusing to contribute to the care costs of the spouse needing Medicaid. A Medicaid-compliant annuity converts countable assets into an income stream for the healthy spouse, keeping those assets out of Medicaid’s calculations. These annuities must be irrevocable, immediate, and not exceed the recipient’s life expectancy.

4. Sibling or Caregiver Exceptions

You can transfer your home to a sibling or adult child without penalty if they meet specific criteria. For a sibling, they must have an equity interest in the home and have lived there for at least one year before your nursing home placement. For a child, they must have lived in your home for at least two years and provided care that delayed your need for a nursing home. These exemptions protect the home from MERP but require careful documentation to avoid penalties.

5. Qualified Income Trusts (QITs)

If your income exceeds Medicaid’s limit, a QIT can help. Excess income is funneled into the trust, which is then used to pay for your care, allowing you to meet eligibility requirements. This is particularly useful for Nursing Home Medicaid or HCBS Medicaid Waivers and doesn’t typically affect asset protection strategies.

6. Converting Assets

You can convert countable assets into exempt ones. For example, prepaying funeral expenses through an irrevocable funeral trust or making home improvements (like a new roof) on an exempt primary residence can reduce countable assets without violating Medicaid rules. Personal belongings and one vehicle are also often exempt, depending on state regulations.

Key Considerations:

– Timing and Penalties: Most strategies are more effective if implemented well before a crisis, as Medicaid’s 5-year look-back period penalizes last-minute asset transfers. In a crisis, you may face a period of ineligibility, but some assets can still be saved with careful planning.

– State Variations: Medicaid rules vary by state, so strategies like Lady Bird Deeds or spousal refusal may not be available everywhere. Always check local regulations.

– Professional Guidance: Crisis Medicaid planning is complex and often requires an elder law attorney to navigate regulations, avoid penalties, and ensure compliance. Missteps, like improper gifting, can lead to disqualification or financial loss.

– Risks of Gifting: Transferring assets to family members can backfire if they face legal or financial issues, such as divorce or creditors. It also means you lose control over those assets, which may not be ideal if you need them later.

These strategies aim to balance immediate care needs with preserving assets for your children and grandchildren. However, the effectiveness of each option depends on your specific financial situation, state laws, and how quickly you need Medicaid coverage. Consulting an elder law attorney is strongly recommended to tailor a plan to your circumstances.

Schroeder Law Group serves clients from their Hillsboro Ohio offices located at 338 West Main Street Hillsboro, Ohio. Schroeder Law’s attorneys help clients with estate planning. The information in this article is intended to educate you and does not create an attorney-client relationship. We are lawyers but not your attorney unless you schedule a strategy session and retain us using the link on this website or by calling (937) 402-2348.

Category: Asset Protection

Many people facing the prospect of long-term care consider gifting assets to their children as a way to qualify for Medicaid assistance. While this may seem like a clever strategy to protect family wealth, it can lead to severe consequences and jeopardize your ability to receive necessary care. Understanding the risks involved is crucial before making any hasty decisions about transferring assets.

Medicaid’s Lookback Period

One of the primary dangers of gifting assets to children is running afoul of Medicaid’s lookback period. When you apply for Medicaid, the program scrutinizes your financial transactions for the previous five years. Any gifts or transfers of property made during this period for less than fair market value can trigger penalties and delay your eligibility for benefits.

The lookback period is designed to prevent people from impoverishing themselves on paper to qualify for Medicaid while preserving their wealth for heirs. If Medicaid determines that you transferred assets within the five-year window, you may face a penalty period during which you’re ineligible for benefits.

Calculating the Penalty Period

The length of the penalty period depends on the value of the assets transferred. Medicaid divides the total value of improperly transferred assets by the average monthly cost of nursing home care in your state. For example, if you gifted $120,000 to your children and the average monthly cost of care is $12,000, you could face a 10-month period of ineligibility.

During this penalty period, you would be responsible for paying for your own care out of pocket. This can quickly deplete any remaining savings and leave you in a precarious financial situation.

Loss of Control Over Assets

When you gift assets to your children, you lose legal control over those resources. Even if your children intend to use the assets for your benefit, there’s no guarantee they will do so. Life circumstances can change, and your children may face their own financial difficulties, addiction issues, divorces, or legal troubles that put your former assets at risk. These assets would be vulnerable to the predators and creditors attacking your children.

Additionally, gifted assets could impact your grandchildren’s eligibility for financial aid for college. The unintended consequences of asset transfers can ripple through multiple generations of your family.

Tax Implications for Your Children

Transferring appreciated assets like real estate or stocks to your children can have negative tax consequences for them. When you gift these assets, your children inherit your original cost basis. If they later sell the assets, they may face significant capital gains taxes that could have been avoided if they had inherited the assets through your estate instead.

Fraudulent Conveyance Risks

In some cases, nursing homes or care facilities may pursue legal action against family members who received asset transfers. If a facility believes transfers were made to avoid payment for care, they may sue for fraudulent conveyance. This can result in judgments against your children, forcing them to repay the value of the gifted assets.

Exceptions to Transfer Penalties

While most asset transfers within the lookback period are penalized, there are some exceptions. For example, transfers to a spouse or to a trust for a disabled child are generally allowed without penalty. Additionally, in some cases, you may be able to transfer your home to certain family members, such as a child who has been your caregiver for at least two years.

Alternative Strategies for Asset Protection

Instead of outright gifting, there are more sophisticated strategies for protecting assets while still qualifying for Medicaid. These may include:

1. Irrevocable Trusts: Properly structured irrevocable trusts can protect assets while potentially avoiding lookback period penalties if established early enough.

2. Medicaid-Compliant Annuities: These financial products can convert countable assets into an income stream that may not affect Medicaid eligibility.

3. Spend-Down Strategies: Using assets to pay off debts, make home improvements, or purchase exempt assets can be a legitimate way to reduce countable resources.

The Importance of Professional Guidance

Navigating Medicaid’s complex rules and regulations requires expert knowledge. Working with an experienced elder law attorney or Medicaid planning specialist is crucial to developing a strategy that protects your assets without jeopardizing your eligibility for benefits.

These professionals can help you understand the specific rules in your state, as Medicaid regulations can vary. They can also assist in developing a comprehensive plan that takes into account your unique financial situation and care needs.

Conclusion

While the desire to preserve family wealth is understandable, gifting assets to children in an attempt to qualify for Medicaid is fraught with risks. The potential for severe penalties, loss of control over assets, and unintended tax consequences make this strategy dangerous and often counterproductive.

Instead of resorting to hasty asset transfers, take the time to explore legal and ethical Medicaid planning strategies. With proper guidance and advance planning, it’s often possible to protect a portion of your assets while still qualifying for the care you need. Remember, the goal should be to ensure you receive proper care while also leaving a legacy for your family – not to impoverish yourself or put your children at financial risk.

Ultimately, the best approach to Medicaid planning is one that balances your need for care with your desire to preserve assets for your heirs. By understanding the rules and working with knowledgeable professionals, you can develop a plan that achieves your goals without running afoul of Medicaid regulations.

It’s important to note that Medicaid rules can be complex and may vary. Consulting with an experienced elder law attorney in Ohio is crucial to ensure proper establishment and compliance with state-specific regulations. Schroeder Law Group helps prepare strategic estate plans for clients from our Hillsboro, Ohio office, serving clients from nearby Mount Orab, Lynchburg, Georgetown, West Union, Washington Court House, Leesburg and Wilmington, Ohio.

Please schedule a strategy session for specific advice or go see another estate planning attorney. The above information is provided for informational purposes and you should not make any decisions about a Medicaid Asset Protection Trust or any other estate plan without consulting an attorney.